Showing posts with label industrial. Show all posts

Thursday, 19 November 2020

Industrial sensors market analysis of covid-19 impact

 The report "Industrial Sensors Market with Covid-19 impact by Sensor (Level Sensor, Image Sensor, Gas Sensor, Pressure Sensor, Position Sensor, Temperature and Humidity & Moisture Sensor), Type, End-use industry, and Geography - Global Forecast to 2025", size is expected to grow from USD 18.2 billion in 2020 to USD 29.0 billion by 2025, at a CAGR of 9.8%. Growing popularity of industrial 4.0 and IoT and increasing demand of industrial robotics are the key factors driving the growth of the Industrial Sensors market.

Download PDF Brochure:-
https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=108042398

Covid-19 Impact in the Industrial sensors market

The outbreak of the COVID-19 pandemic has adversely impacted the growth of several industries, including manufacturing, oil & gas, and many others. Oil & gas is a major end-use industry of the industrial sensor market. Due to COVID-19, many ongoing or new projects across the oil and gas value chain are likely to face many challenges in terms of project execution, planning, and risk management. More than 2000 EPC oil & gas projects across various segments, including LNG, petrochemical, and oil storage & refineries, have to come to a halt or are delayed due to the pandemic. The energy research firm Rystad Energy has predicted that a 25% decline in oil prices could result in a cut in oil and gas investments by USD 30 billion globally.

The automotive and transportation is also a major end-use industry of the industrial sensors market. Many countries, including the US, China, Japan, and South Korea, have stopped the production of automobiles due to the COVID-19 pandemic.

Apart from oil & gas and automotive many other industries across the world, including power generation and mining, have suspended production activities in almost all the countries due to the pandemic. This is expected to lower the demand for industrial sensors and significantly impact the market growth during the forecast period.

Contact type to dominate Industrial Sensors market, in 2020

The market for contact type sensors is estimated to account for a larger share of the overall Industrial Sensors market, in 2019. Contact level sensors involve physical contact between the device (comprising contact type industrial sensor) and media. The technologies used in contact type level sensors are magnetoresistive, vibratory probe, hydrostatic, magnetic and mechanical float, pneumatic, rotating paddle, resistive chain, and weight and chain. Some of the most common types of contact type sensors are temperature sensors, pressure sensors, force sensors, flow sensors, etc.

APAC to hold largest share of Industrial Sensors market in 2019

In terms of value, APAC  led the Industrial Sensors  market in 2019, accounting for the largest share of the overall Industrial Sensors market, by region. As China is among the major industrial areas in the world, the industrial sensors market in APAC is expected to record the largest market share by 2025. Key countries for the industrial sensors market in APAC are China and Japan. APAC has vast opportunities for revenue generation from the industrial sector in the coming years.

Rockwell Automation (US), Honeywell (US), Texas Instruments (US), Siemens (Germany), Bosch Sensortec (US), Panasonic (Japan), STMicroelectronics (Switzerland), First Sensor (Germany), Amphenol Corporation (US), Integrated Device Technology (US), TE Connectivity (Switzerland), Omega Engineering (US), Sensirion (Switzerland), Ams AG (Austria), Microchip (US), NXP Semiconductors (Netherlands), Teledyne Technologies Incorporated (US), Figaro Engineering inc (Japan), and Safran Colibrys SA (Switzerland)   are a few major companies dominating the industrial sensors  market.

Don’t miss out on business opportunities in Industrial Sensors Market. Speak to our analyst and gain crucial industry insights that will help your business grow.

About MarketsandMarkets™

MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 7500 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Aashish Mehra
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Friday, 21 August 2020

Which are the Top Applications in Lithium Ion Battery Market?

 According to the new market research report "Lithium-Ion Battery Market by Type (Li-NMC, LFP, LCO, LTO), Power Capacity (0-3,000 mAh, 3,000 mAh-10,000 mAh, 10,000 mAh-60,000 mAh, above 60,000 mAh), Industry (Consumer Electronics, Automotive, Industrial), Voltage, Region – Global Forecast to 2025", is estimated to grow from USD 44.2 billion in 2020 to reach USD 94.4 billion by 2025 at a CAGR of 16.4%. The lithium-ion battery industry is likely to exhibit lucrative growth potential during the forecast period. Factors such as increasing demand for plug-in vehicles, growing need for automation & battery-operated material-handling equipment in industries, increasing demand for smart devices and other industrial goods, and high requirement of lithium-ion batteries for various industrial applications are driving the growth of the lithium-ion battery market.

Download PDF Brochure:-
https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=49714593

Lithium-Ion Battery Market and Top Applications

  • Consumer Electronics – Continuous technological developments in consumer electronics have boosted the growth of lithium-ion battery market. Li-ion batteries are in high demand for the consumer electronics application because they offer higher density, better durability, offers less recharge time, and more energy storage than other batteries. Lithium-ion batteries are a state-of-the-art power source for all modern consumer electronic devices. Being environment-friendly, lithium-ion batteries are widely accepted by electronics manufacturers.
  • Automotive − The automotive industry is expected to be one of the major segments for lithium-ion batteries. Battery-driven vehicles such as electric vehicles, e-bikes, and automated guided vehicles, are major consumers of lithium-ion batteries. The market for these vehicles is expected to grow due to increasing adoption and awareness of EVs, partly driven by the adoption of various environmental norms and emission regulations. This has resulted in an increase in the demand for Li-ion and Ni-Mh batteries.
  • Industrial – Lithium-ion batteries are used in various industrial applications. These batteries provide advantages in terms of carbon emissions and safety in underground environments. Batteries with high energy density and longer backup are required to improve the efficiency and performance of industrial equipment. Rapid infrastructural growth and support from governments and industry associations for the adoption of lithium-ion batteries are boosting the demand for construction and mining equipment, which is further leading to the growth of lithium-ion batteries in the industrial sector.
  • Power − The power industry is working on generating renewable energy and storing it for multiple uses. Attributes such as low cost, less space required for installation, and low self-discharge rate are some of the driving factors for the adoption of lithium-ion batteries in smart grid and renewable energy storage systems. The lithium-ion battery technology is being used in power plants to achieve maximum efficiency. These batteries are more resistive to extreme temperature situations, making them suitable for use in remote locations and for thermal management options.

"Market for Lithium Nickel Manganese Cobalt is expected to grow at a higher rate during the forecast period."

The energy density of NMC batteries is its primary strength. It achieves this energy density with excellent stability due to the use of an optimum ratio of nickel manganese and cobalt. It also has a good charge and discharge cycle. These features enable its application in industries such as automotive.

NMC is used in batteries of laptops, mobile phones, tablets, automotive, power tools, and electrical storage systems. It is lightweight and can better serve slimmer and lighter tablets and smartphones. This property will lead to the gradual replacement of LCO and NCA cathode materials in batteries of notebooks, mobile phones, and tablets.

NMC is also used in HEV, EV, and PHEV as it offers higher safety, along with other desired properties. These advantageous properties of NMC are expected to increase its market share in the next five years and ideally positioned it to be the best material available in this industry.

Lithium-ion battery market for power capacity range 3,000–10,000 mAH is expected to grow at the highest rate during the forecast period."

Lithium-ion batteries' heavy power capacity makes it useful in electric vehicles and industrial uses. The increasing market of consumer electronics and smartphones is driving the need for batteries with high power capacity that can keep the device running for long hours and, at the same time, giving an optimum experience of the device due to large screen and power back up service.

"Lithium-ion battery market for automotive is expected to hold the largest market during the forecast period."

Increasing adoption and awareness of EVs, government initiatives, and regulations supporting the adoption of EVs around the world are the factors that are driving the growth of the lithium-ion battery market. The market for these vehicles is expected to grow in the near future, partly driven by the adoption of various environmental norms and emission regulations. This has increased the demand for Li-ion batteries.

"Lithium-ion battery market for above 36 V segment is expected to hold the largest market during the forecast period."

The majority of the manufacturers prefer above 36V lithium-ion batteries as they support and power high-current applications, and have a long life span. Lithium-ion batteries with this voltage range are the most demanded and used as they are equipped with high capacity and unmatched capabilities. These batteries are used in electric vehicles, marine, power, military, telecom, etc. These batteries offer higher power, longer life, and robust safety compared to lead-acid batteries, which boosts its demand in the market. These batteries feature a built-in automatic battery management system (BMS), which keeps the battery running at peak performance while preventing overcharging, overheating, and maximizing cell cycle life.

APAC held the largest size of the lithium-ion battery market during the forecast period

APAC held the largest size of the lithium-ion battery industry in 2018. APAC is home to a large number of semiconductor and electronics companies and the increasing trend to implement high power battery, and safety with low energy wastage are expected to open up new market opportunities for lithium-ion battery in APAC. China and India are the fastest-growing economies in the world.

Demand for lithium-ion batteries is very high in Asia Pacific owing to the ever-increasing population and its need for consumer electronics. The market in China is expected to grow mainly because of the huge number of lithium-ion battery manufacturing companies in China and Japan. A major share of lithium-ion batteries is manufactured in APAC—specifically in China, Japan, and South Korea.

Key players operating in the lithium-ion battery market include BYD Company (China), LG Chem (South Korea), Panasonic (Japan), Samsung SDI (South Korea), BAK Group (China), GS Yuasa Corporation (Japan), Hitachi (Japan), Johnson Controls (Ireland), Toshiba (Japan), Lithium Werks (The Netherlands), CALB (China), Saft Groupe, (France), VARTA Storage (Germany), Farasis Energy (California), and Sila Nanotechnologies (California).

Don’t miss out on business opportunities in Lithium-Ion Battery Market. Speak to our analyst and gain crucial industry insights that will help your business grow.

About MarketsandMarkets™

MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 7500 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Aashish Mehra
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Wednesday, 24 June 2020

Industrial Valve Market | Challenge: Minimization of lead times

The report "Industrial Valves Market by Size, Valve Type (Ball, Butterfly, Gate, Globe, Check, Plug), Material Type (Cast Iron, Steel, Cryogenic, Alloy Based), Industry (Oil & Gas, Water & Wastewater, Energy & Power), and Geography - Global Forecast to 2023", is anticipated to grow at a CAGR of 3.9% from 2018 to 2023, to reach USD 85.1 billion by 2023. The growing demand for industrial valves from oil & gas production facilities and smart city development initiatives undertaken across geographies are some of the major factors fueling the growth of this market.

Challenge: Minimization of lead times

Product availability and its lead time are the most influencing factors for purchasing valves. Average lead time of valves is 18 weeks, which can vary with respect to valve type, valve material, and its application.
Generally, industrial valves are divided into 3 categories: commodity valves, advanced products, and specialty/customized products. Lead time plays a vital role in advanced and specialty/customized products. Industry players strive to quote a minimum lead time in their proposals to win the order. Successful order fulfillment with promised lead time depends on various factors such as supply–demand analysis, raw material procurement capacity, engineering capacity, and component stocking capacity of a manufacturer. Although the average lead time of industrial valves is 18 weeks, there are a few Chinese valve manufacturers who are using lead time as their differentiating strategy. These Chinese manufacturers are offering advanced and specialty/customized valves in around 10 weeks.
Industry players are trying to overcome the challenge of minimizing their lead time by using a number of lean and agile approaches. It is advisable that industry players should maintain a sound relationship with entities present in the value chain of their business. This approach can help industry players to gather the required inventory for valves easily at the lowest turn-around time; by this approach, industry players can tackle this challenging pain point of the valve industry.

Asia Pacific Anticipated to Be the Leading Revenue Contributor to the Industrial Valves Market

APAC is projected to be the leading market for industrial valves during the forecast period. There is an increase in power generation, which is a direct result of the rapidly growing population and industrialization. The growth of energy & power, oil & gas, construction, chemicals, and pharmaceuticals industries and the increasing demand for new and improved wastewater treatment systems are some of the major factors fueling the growth of the industrial valves market in this region.
Some of the key manufacturers of industrial valves are Wier group (UK), Flowserve Corporation (US), Emerson Electric Corporation (US), IMI Plc (UK), and Cameron –Schlumberger (US).
About MarketsandMarkets™
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 7500 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.
Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.
MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.
Contact:
Mr. Aashish Mehra
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Wednesday, 17 June 2020

Temperature Sensor Market | Expanding automobile & industrial manufacturing sector to drive the demand

The global temperature sensor market size is projected to grow from USD 6.3 billion in 2020 to USD 8.8 billion by 2027, recording a CAGR of 4.8%. The temperature sensor industry growth is driven mainly by increasing penetration of temperature sensors in advanced and portable healthcare equipment, growing demand for temperature sensors in the automotive sector, and rising adoption of home and building automation systems.
Expanding automobile & industrial manufacturing sector to drive the demand for temperature sensors in APAC during the forecast period
The temperature sensor market in APAC is projected to grow at the highest CAGR during the forecast period. China, India, South Korea, and Japan are the major contributors to the growth of the temperature sensor industry in APAC.
Expanding automobile and industrial manufacturing, in particular, is generating massive demand for temperature sensors. Also, robust demand for consumer equipment, including portable healthcare electronics and white goods, is expected to foster the demand for temperature sensors. Furthermore, the increasing adoption of automated technologies across diverse industries, especially in automotive and food & beverages, is likely to generate demand for temperature sensors in APAC. Other factors driving the temperature sensor market in APAC include escalating demand for temperature sensors from the overseas markets of North America and Europe.
Key players operating in the temperature sensor market include Honeywell (US), TE Connectivity (Switzerland), Texas Instruments (US), Endress+Hauser (Switzerland), Siemens (Germany), Texas Instruments (US), Dwyer Instruments (US), Maxim Integrated (US), WIKA Instrument (Germany), Amphenol (US), and Emerson (US). The majority of the companies focus on organic and inorganic growth strategies such as product launches and developments, mergers and acquisitions, agreements, contracts, partnerships, collaborations, and expansions to increase their revenue.
Non-contact temperature sensor to witness a higher CAGR during the forecast period
The non-contact temperature sensor is projected to record the higher CAGR in the temperature sensor market from 2019 to 2027. Non-contact sensors measure the surface temperature of a body or an object to be identified without any physical contact between the sensor and the object. These temperature sensors are mainly used for small, moving, and inaccessible objects/sources/devices.
Digital output to hold the largest share in the temperature sensor industry during the forecast period
The temperature sensor comprises analog and digital outputs. The digital output segment is projected to hold a larger share in the temperature sensor market during the forecast period. Temperature sensors with digital output have several advantages over sensors with analog output and are especially suited for remote applications. Digital temperature sensors find use in medical, aerospace, test and measurement equipment, and industrial automation.

Get in-depth analysis of the COVID-19 impact on the Temperature Sensor Market

Benchmarking the rapid strategy shifts of the Top 100 companies in the Temperature Sensor Market
Request for Special Pricing@
https://www.marketsandmarkets.com/RequestCOVID19.asp?id=522
About MarketsandMarkets™
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 7500 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.
Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.
MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.
Contact:
Mr. Aashish Mehra
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Thursday, 16 April 2020

know the COVID-19 impact on the Industrial Sensors Market

The industrial sensors market is expected to be valued at USD 16.0 billion in 2018 and is likely to reach USD 21.6 billion by 2023, at a CAGR of 6.16% during the forecast period. The study involved 4 major activities to estimate the current market size for industrial sensors. Exhaustive secondary research was done to collect information on market, peer market, and parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.

Download PDF brochure:-

Level sensor to hold largest share of industrial sensors market in 2018

Based on sensor, level sensor leads the industrial sensors market as major applications of level sensors, such as manufacturing and process industries, semiconductor manufacturing, automotive manufacturing, and aerospace and defense manufacturing, occupy a huge share in the industrial sensors market. Also, average selling price of level sensors is highest when compared with other types of sensors covered in this report.

Market for noncontact sensors to grow at higher CAGR during forecast period

Noncontact industrial sensors is a faster growing segment of the industrial sensors market. Increasing penetration of remote sensing and wireless sensing attributes to the growth of noncontact sensors in the industrial sensors market. The wireless sensors market is increasing due to factors such as increasing penetration in industrial automation applications; growing adoption of wearables in industrial facilities; emerging concepts, such as smart factory; and increasing applications in pharmaceuticals and mining industries and petroleum refineries.

APAC to account for largest market during forecast period


APAC is expected to hold the largest share of the industrial sensors market in 2018. APAC is the largest market for industrial sensors because of the presence of China in this region. China’s manufacturing output is the largest in the world. Therefore, China is among the world’s largest manufacturer and industrial producers. It is one of the major manufacturers of consumer electronics, automobiles, etc.

Key Market Players


A few major players operating in the industrial sensors market are Rockwell Automation (US), Honeywell (US), Amphenol Corporation (US), Texas Instruments (US), Panasonic (Japan), STMicroelectronics (Switzerland), First Sensor (Germany), and Siemens (Germany). Rockwell delivers a wide range of solutions and services for applications such as food & beverages, life sciences, oil & gas, mining, cement, metals, pulp & paper, and water & wastewater. The company offers start-to-end industrial services to its end users. The available solutions offer the company an advantage over its competitors for increased growth. The company adopts both organic and inorganic growth strategies. In the last 3 years, Rockwell Automation offered 2 products related to the industrial sensors segment.

About MarketsandMarkets™

MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 7500 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Sanjay Gupta
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Tuesday, 26 November 2019

Current Sensor Market | EV/HEV Applications Boosting Sales of Current Sensors in Automotive Industry

The current sensor market is expected to grow from USD 2.4 billion by 2019 to USD 3.6 billion by 2024 at a CAGR of 8.34%. The increasing use of battery-powered applications and renewable energy forms, and growing market for Hall effect current sensors are among the key driving factors for this market. Moreover, the growth of automotive electronic control systems and new vehicle technologies, and large-scale commercialization of IoT and IIoT are among the other factors fueling the market growth.
Automotive industry to hold largest share of current sensor market by 2019
The automotive industry accounted for the largest share of the current sensor market in 2018. The growth of the market for the automotive segment is attributed to the high volume of current sensors being used in automotive vehicles worldwide. Further, this growth is also ascribed to the increasing number of electric vehicles and hybrid vehicles (EV and HEV). The growth of the electric vehicle industry is driven by the increasing adoption of hybrid and electric cars in China, Germany, the US, and other countries. China was the largest market for electric cars in 2018, with 380 thousand electric cars registered. The US is the second-largest market for electric cars with 190 thousand units registered.

Current Sensor Market, by End User

  • Automotive
  • Consumer Electronics
  • Telecom And Networking
  • Healthcare
  • Industrial
  • Energy
  • Others (Railways, Building Automation, Aerospace & Defense)

APAC to account for largest share of current sensor market during forecast period

APAC is expected to account for the largest share of the current sensor market during the forecast period. The market in this region is also expected to witness significant growth during 2019–2024. The population growth and rapid urbanization in developing economies, such as China and Japan, have prompted the speedy development in the region, which will boost the demand for current sensor from verticals such as energy, automotive, telecom and networking, industrial, and healthcare.

Key Market Players

Key players in the current sensor market include Asahi Kasei Microdevices (Japan), Melexis (Belgium), Allegro Microsystems (US), Siliocn Labs (US), LEM International (Switzerland), Sensitec (Germany), Koshin Electrin (Japan). Asahi Kasei Microdevices (Japan) is a leader in the current sensing industry. The company has shown consistent growth in the market by demonstrating capability to serve new markets, and its product launches and promotional activities have boosted its revenue growth.
About MarketsandMarkets™
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 7500 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.
Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.
MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.
Contact:
Mr. Shelly Singh
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Sunday, 25 August 2019

Growth in Demand for industrial automation in manufacturing to drive the global smart manufacturing market by 2022

Smart manufacturing is a powerful disruptive force with the potential to restructure the current competitive landscape and produce a new set of market leaders. It is a combination of various technologies and solutions, which, if implemented in a manufacturing ecosystem, is termed smart manufacturing.

The smart manufacturing market is expected to be worth USD 170.78 billion by 2018 and USD 299.19 billion by 2023, growing at a CAGR of 11.9% from 2018 to 2023. Factors that drive the growth of the market include Industry 4.0, increasing use of industrial automation in manufacturing, government investments supporting industrial automation, rising emphasis on regulatory compliances, increased complexities in supply chain, and increasing demand for software systems that reduce time and cost.

• Download PDF Brochure:-
https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=105448439

Increasing use of industrial automation in manufacturing to drive the global smart manufacturing demand by 2022

Amidst sluggish economic growth, increasing productivity and lowering manufacturing costs have become quite critical for manufacturers all over the world. On account of this, manufacturing companies are witnessing intense competition, and this trend is expected to continue during the forecast period. To better optimize resources and reduce costs, manufacturers are actively focusing on adopting industrial automation and enabling technologies.

Enterprise manufacturing intelligence (EMI) system analyzes manufacturing data collected from various sources across an organization. This information is then utilized to track performance against relevant metrics. Integration of advanced HMI solutions and connectivity technology with various industrial automation equipment has tremendously increased quality, productivity, and mobility of plant assets. Adoption of industrial automation equipment, such as industrial robots, field devices, and smart equipment, has increased significantly among manufacturers from various industries such as food & beverages, oil & gas, metal & mining, automotive, semiconductor & electronics, and aerospace & defense. Integration of solutions such as ERP, SCADA, PLM, and PLC with MES enhances efficiency of processing and gives effective output. Manufacturing execution system (MES) is capable of performing multiple activities and delivers efficiency by checking quality as well as production optimization. It tracks processes and procedures with the help of industrial automation. MES helps optimize production costs by reducing wastes, downtime, rework, and defects during manufacturing.

The popularity of cloud-based solutions is increasing rapidly as they help manufactures operate modern and advanced software without any need for separate om-premise infrastructure. Implementation of PAM software is a complex process as manufacturers deal with various production as well as automation assets that interact with each other. Cloud-based deployment offers manufacturers centralized process execution and coordination advantages in a cost-efficient package. A cloud-based WMS allows warehouse operators to track inventory more easily and ensure that necessary stock is available to fulfill customer orders. If there is any unpredicted demand for certain products, cloud computing makes it easier to respond quickly by enabling communicating with suppliers and staff to get the required stock.

About MarketsandMarkets™

MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 7500 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Shelly Singh

MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441 

Monday, 19 August 2019

What are the leading industries of current sensors?

The automotive, healthcare, industrial, and energy sectors, and the consumer electronics industry, among others, are the major end users of current sensors.
The current sensor market is expected to reach USD 3.6 billion by 2024 from USD 2.4 billion by 2019, at a CAGR of 8.34% during the forecast period. The growth of this market is mainly attributed to the increasing use of battery-powered applications and renewable energy forms, and growing market for Hall effect current sensors. Moreover, the growth of automotive electronic control systems and new vehicle technologies, and large-scale commercialization of IoT and IIoT are among the other factors fueling the growth of this market.
Automotive industry to hold largest share of current sensor market by 2019
The automotive industry accounted for the largest share of the current sensor market in 2018. The growth of the market for the automotive segment is attributed to the high volume of current sensors being used in automotive vehicles worldwide. Further, this growth is also ascribed to the increasing number of electric vehicles and hybrid vehicles (EV and HEV). The growth of the electric vehicle industry is driven by the increasing adoption of hybrid and electric cars in China, Germany, the US, and other countries. China was the largest market for electric cars in 2018, with 380 thousand electric cars registered. The US is the second-largest market for electric cars with 190 thousand units registered.
Closed loop to hold larger share and witness significant CAGR in market during forecast period
The closed-loop segment accounted for a larger share of the current sensor market in 2018. This growth is attributed to the advantages of this type over open-loop type; these include high accuracy and linearity, low gain drift, wide bandwidth, and fast response time. Owing to this, closed-loop current sensors have major demand from the industrial and automation sectors. Closed-loop current sensors are used in industries such as aerospace & defense, automotive, medical, railway, automotive, and consumer electronics, where accuracy and response time are the major requirements. These sensors are generally used in motor drive controllers, photovoltaic systems, generator/alternator monitoring and controlling system, robotics, UPS and telecommunication power supplies, welding power supplies, and frequency and voltage inverters.
APAC to hold largest share of current sensor market by 2019
A few key players operating in the current sensor market are Asahi Kasei Microdevices (Japan), Melexis (Belgium), Allegro Microsystems (US), Infineon Technologies (Germany), and Honeywell (US).
About MarketsandMarkets™
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 7500 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.
MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.
Contact:
Mr. Shelly Singh
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441 

Monday, 13 May 2019

Industrial Sensors: Market for noncontact sensors to grow at higher CAGR during forecast period

The industrial sensors market is expected to be valued at USD 16.0 billion in 2018 and is likely to reach USD 21.6 billion by 2023, at a CAGR of 6.16% during the forecast period. The study involved 4 major activities to estimate the current market size for industrial sensors. Exhaustive secondary research was done to collect information on market, peer market, and parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.


Download PDF Brochure:-
https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=108042398

 
Noncontact industrial sensors is a faster growing segment of the industrial sensors market. Increasing penetration of remote sensing and wireless sensing attributes to the growth of noncontact sensors in the industrial sensors market. The wireless sensors market is increasing due to factors such as increasing penetration in industrial automation applications; growing adoption of wearables in industrial facilities; emerging concepts, such as smart factory; and increasing applications in pharmaceuticals and mining industries and petroleum refineries.


APAC expected to hold largest share of industrial sensors market in 2018


APAC is expected to hold the largest share of the industrial sensors market in 2018. China and Japan are the key countries contributing to the growth of the industrial sensors market in APAC. APAC is the largest market for industrial sensors because of the presence of China in this region. China’s manufacturing output is the largest in the world. It is one of the major manufacturers of consumer electronics, automobiles, etc.

 North America is expected to account for the second-largest share of the industrial sensors market throughout the forecast period. The US currently accounts for the largest share of the industrial sensors market in North America, followed by Canada and Mexico.

A few major players operating in the industrial sensors market are Rockwell Automation (US), Honeywell (US), Amphenol Corporation (US), Texas Instruments (US), Panasonic (Japan), STMicroelectronics (Switzerland), First Sensor (Germany), and Siemens (Germany). 

About MarketsandMarkets™
 
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 7500 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Shelly Singh
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Monday, 15 April 2019

Power Electronics Market Worldwide Trends, Specification, Growth Drivers, Industry Analysis - Global Forecast to 2023

The power electronics market was valued at USD 36.93 Billion in 2017 and is expected to reach USD 51.01 Billion by 2023, at a CAGR of 5.5% during the forecast period. The base year considered for the study is 2017, and the forecast period considered is 2018–2023. This report provides a detailed analysis of the power electronics market based on device type, material, application, vertical, and region. The report forecasts the market size, in terms of value, for various segments with regard to 4 main regions—North America, Europe, APAC, and RoW. It strategically profiles the key players and comprehensively analyzes their market rankings and core competencies, along with detailing the competitive landscape for the market leaders.

ICs expected to hold a major share of the power electronics market during the forecast period

Power ICs are suitable for high-frequency range, high power amplification, and microwave radiation applications. Currently, the power ICs market for industrial, ICT, and aerospace & defense verticals is fueled by various high-power and high-frequency applications such as RF, high-frequency wireless communication, RADAR, satellite communication, electronic warfare, radio communication, and microwave radiation fields. Moreover, the increasing demand for ASICs and PMICs for reducing power consumption propels the growth of the market.

 
Market for transportation application to hold a major share of the power electronics market between 2018 and 2023

The growth of the market is attributed to the growing use of electronic devices in the automotive vertical for charging stations, car safety, authentication, mobile security, and others. Moreover, large-scale production of HEVs and EVs and the rising demand for electric vehicle charging stations are expected to make transportation the largest revenue sector for the power electronics industry in the near future. Moreover, governments’ mandate to develop environmentally friendly vehicles is expected to create opportunities for the power electronics market.

Automotive vertical expected to hold major share of the power electronics market between 2018 and 2023

Power electronics play a vital role in the automotive segment as they help optimize the use of electrical energy. Increasing concerns over environmental pollution and sustainable growth are boosting the growth of the market for hybrid electric vehicles and high-end automobiles. Power electronic components, including MOSFETs and IGBTs, are used as a power electronic switch in vehicles to increase the fuel efficiency of the vehicle.

APAC expected to hold major share of the power electronics market between 2018 and 2023

APAC has been the fastest-growing region in terms of power electronic products and solutions compared to other regions. The growth is attributed to the presence of large number of automotive and consumer electronics manufacturers in APAC and growing demand for power electronic devices in automotive and consumer applications. Moreover, the growing demand of industrial and energy & power verticals for power electronic devices helps the market to grow further in the region.

The value chain of the power electronics market comprises raw material suppliers, manufacturers, investors, and distributors. Players operating in the power electronics market include Infineon Technologies (Germany), Texas Instruments (US), On Semiconductor (US), STMicroelectronics (Switzerland), Mitsubishi Electric (Japan), Fuji Electric (Japan), Renesas Electronics (Japan), Toshiba (Japan), NXP Semiconductors (The Netherland), Vishay Intertechnology (US), Maxim Integrated Products (US), SEMIKRON (Germany), ABB (Switzerland), Hitachi, (Japan), Analog Devices (US), ROHM Semiconductor (Japan), Microsemi (US), Littelfuse (US), Microchip Technology (US), and Danfoss (Denmark).

About MarketsandMarkets™
 
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 5000 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Shelly Singh
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Thursday, 21 February 2019

$34 Billion Delivery Robots Market - Global Forecast to 2024

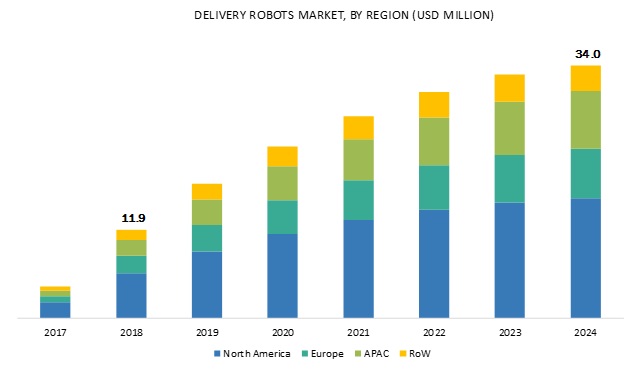
The delivery robots market is expected to grow from USD 11.9 million in 2018 to USD 34.0 million by 2024, at a CAGR of 19.15% during the forecast period. The reduction in last-mile delivery costs due to the adoption of these robots is the key factor driving the growth of the delivery robots market. The increase in venture funding is another driving factor for the market.

Delivery robots with load carrying capacity of more than 50.00 kg to hold the largest market size by 2018

The high rate of adoption of delivery robots with load carrying capacity of more than 50.00 kg for e-commerce applications in the retail industry is the key factor driving the market. Apart from e-commerce applications, robots with a load carrying capacity of more than 50.00 kg are mainly used to deliver groceries and heavy parcels ordered by online shoppers. However, robots under this category need to follow a comparatively large number of regulations than the robots belong to other 2 categories because delivery robots with more than 50.00 kg load carrying capacity travel on streets rather than sidewalks, thereby requiring effective traffic management.

The market for delivery robots with higher than 6 kph speed to grow at the highest CAGR during the forecast period

The speed limit has been the key factor for the manufacturer and the lawmaker as it proves to be vital for the safety of human commuters. However, the low speed will affect the operational efficiency, and it would result in the high cost of delivery. The speed limit allowed for a pedestrian robot is generally up to 6 kph. Technologically advanced delivery robots have made it possible to deliver different kinds of items quickly and efficiently. This factor is expected to fuel the growth of the market for delivery robots with higher than 6 kph speed during the forecast period.

4-wheeled delivery robots to dominate the market in 2018

4-wheeled delivery robots are expected to dominate the market in 2018 owing to their capability to well balance the robot. Reducing the distance between the front and rear set of wheels will result in better zero-radius turning in any desired direction with 4-wheeled robots. Hence, most of the robotics companies across the world offer delivery robots with 4 wheels, which are more efficient in rotating in-place. However, the market for 6-wheeled delivery robots is expected to grow at the highest CAGR during the forecast period.
Delivery Robots Market

The market in APAC is expected to grow at a significant rate during 2018–2024

APAC countries such as Australia and Japan are currently involved in testing delivery robots. By the end of Q2 of 2019, these countries are expected to commercialize delivery robots developed by them. The growth of the market in APAC is likely to be propelled by the increasing awareness about the potential of delivery robots to provide delivery services with high efficiency and at a reduced cost. Apart from this, the existence of- e-commerce giants, such as Amazon, Walmart, and Alibaba, in the region provides a growth opportunity for the players in the delivery robots market in APAC. Further, with the increased demand and reduced prices of major components such as LiDAR sensors and motors, the market for delivery robots has a promising future in this region.

Key Market Players

A few major companies in the delivery robots market are Starship Technologies (US), JD.com (China), Panasonic System Solutions Asia Pacific (Singapore), Savioke (US), Nuro (US), Amazon Robotics (US), Robby Technologies (US), Boston Dynamics (US), Robomart (US), Eliport (Spain), Dispatch (US), Piaggio Fast Forward (US), Marble (US), TeleRetail (Switzerland), BoxBot (US), and Kiwi Campus (US). Apart from these, players such as House of Battery (US) and Ultralife Corporation (US) supply batteries to key autonomous robot manufacturers, and companies such as Fastree (Switzerland) and Quanergy (US) are the suppliers of light detection and ranging (LiDAR) sensors.

Starship Technologies offers self-driving delivery robots that improve the local distribution of goods and groceries. The company’s vision of zero cost, zero waiting time, and the least adverse impact on the environment have redefined the local delivery chain. The company believes that robots can complete local deliveries within 5–30 minutes from a local hub or retail outlet and with 10–15 times less than the cost of current last-mile delivery alternatives. Robots are overseen by human operators, along with their property to drive autonomously, to ensure safety. The robots developed by the company have covered more than 100,000 miles in more than 100 cities of 20 countries in the world, encountering 15 million people along the way. In June 2018, the company raised the seed capital of USD 25 million, which is likely to be invested in deploying more number of robots in neighborhoods, as well as corporate and university campuses in the US and Europe.

About MarketsandMarkets™
 
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 7500 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Shelly Singh
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Thursday, 14 February 2019

Electric Enclosure Market : Expected To Observe Major Growth By 2023

The electric enclosure market is likely to witness steady growth in the coming years because of the upturn in the oil & gas industry and the demand for hygienic type enclosures valves in the food & beverages industry. The electric enclosure market is expected to grow from USD 5.84 Billion in 2017 to USD 7.91 Billion by 2023, at a CAGR of 6.27% between 2018 and 2023.

Major electric enclosure manufacturers have a tight control on the pricing of the products, which is forcing other manufacturers to reduce the price of products to remain in competition. The electric enclosure industry will witness healthy product development programs and innovations in the coming years.

Among various applications, the power generation & distribution industry is expected to account for the largest size of the overall electric enclosure market between 2018 and 2023. Electric enclosures are used in the power generation & distribution industry in substations to protect critical components and circuitry. Electric enclosures used in oil & gas, metals & mining, and pulp & paper industries are rugged in design and should be able to withstand harsh environmental conditions. Over the past few years, oil & gas products have witnessed strong demand from developing nations. Such continuously increasing demand for oil & gas products is expected to drive the electric enclosure market.

Nonmetallic enclosures are gaining rapid acceptance in oil & gas and metals & mining verticals. This is due to increasing research & development of nonmetallic materials for enclosure application. Extensive research and product development has enabled manufacturers to introduce several new nonmetallic products with favorable and necessary features, which are making nonmetallic enclosures gain acceptance for critical applications.

About MarketsandMarkets™
 
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 5000 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "RT" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Shelly Singh
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Friday, 5 October 2018

Power Electronics Market trends 2018: Industry Analysis to 2023

The power electronics market was valued at USD 36.93 Billion in 2017 and is expected to reach USD 51.01 Billion by 2023, at a CAGR of 5.5% during the forecast period. The base year considered for the study is 2017, and the forecast period considered is 2018–2023. This report provides a detailed analysis of the power electronics market based on device type, material, application, vertical, and region. The report forecasts the market size, in terms of value, for various segments with regard to 4 main regions—North America, Europe, APAC, and RoW. It strategically profiles the key players and comprehensively analyzes their market rankings and core competencies, along with detailing the competitive landscape for the market leaders.

• Download PDF Brochure:-
https://www.marketsandmarkets.com/pdfdownload.asp?id=204729766
 
The power electronics market has been segmented on the basis of device type into discrete, modules, and ICs. The power ICs led the power electronics market in 2017. Power ICs including PMICs and ASICs are primarily used in high-frequency range, high power amplification, and microwave radiation applications.

On the basis of application, the power electronics market has been segmented into power management, drive, UPS, rail traction, transportation, renewable, and others. The power electronics market for the transportation application is expected to grow at the highest CAGR between 2018 and 2023 owing to increasing production of HEVs and EVs and rising demand for electric vehicle charging stations across the globe.

The power electronics market is segmented on the basis of vertical into ICT, consumer electronics, energy and power, industrial, automotive, aerospace and defense, and others. The automotive vertical is expected to grow at the highest CAGR during the forecast period owing to the increasing focus on hybrid electric vehicles (HEVs) and EVs and increasing demand for cars and other passenger vehicles across the globe.

The key strategy adopted by major players to grow in the power electronics market is product launches and developments (between 2015 and 2017). Infineon Technologies (Germany), Texas Instruments (US), ON Semiconductor (US), STMicroelectronics (Switzerland), and Renesas Electronics (Japan) had adopted this strategy. 

Infineon Technologies, one of the global companies, provides semiconductor and system solutions for a wide range of applications such as automotive, consumer, industrial, robotics, energy and power, and so on. Its power product portfolio includes insulated-gate bipolar transistor (IGBT), power metal oxide semiconductor field-effect transistor (MOSFET), diodes, thyristors, silicon carbide (SiC), and other components. For instance, in March 2018, Infineon Technologies established a joint venture with SAIC Motor Corporation Limited (Shanghai) to manufacture power modules for the electric vehicle market in China.

About MarketsandMarkets™
 
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 5000 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "Knowledgestore" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Shelly SinghMarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441

Monday, 23 April 2018

Mobile Substation Market worth 1,136.9 Million USD by 2023

The mobile substation market was valued at USD 742.4 Million in 2017 and is expected to reach USD 1,136.9 Million by 2023, at a CAGR of 7.57% during the forecast period. The base year considered for the study is 2017, and the forecast period is between 2018 and 2023. The objective of the report is to provide a detailed analysis of the mobile substation market based on application and region. 

 
The study also covers qualitative information of various components used in a mobile substation. The report provides detailed information regarding the major factors influencing the growth of the mobile substation market. The report also gives a detailed overview of the value chain in the ecosystem of the mobile substation and analyzes the market trends based on the competitive leadership analysis.
The mobile substation value chain comprises the following phases: Tendering or proposal; design & assembly; transportation & commissioning; and End User. After receiving a proposal for a mobile substation, the company either designs and assembles a mobile substation or outsource it from another player.  Key players in this market are Siemens (Germany), ABB (Switzerland), Eaton (Ireland), General Electric (US), CG Power (India), and MEIDENSHA (Japan).

Other companies covered in this report are Nari Group (China), WEG (Brazil), TGOOD (Hong Kong), Powell Industries (US), AZZ Inc. (US), Elgin Power Solutions (US), Matelec Group (Lebanon), Aktif Group (Turkey), PME Power Solutions (India), EKOS Group (Turkey), Unit Electrical Engineering (UEE) (Canada), Ampcontrol Pty Ltd. (Australia), Efacec (Portugal), Tadeo Czerweny (Argentina), Jacobsen Elektro (Norway), and Delta Star (US).

Scope of the Report:
This report categorizes the global mobile substation market on the basis of application and geography.
Mobile Substation Market, by Application
  • Utilities
  • Industrial
    • Oil & Gas
    • Metals & Mining
    • Others (Construction, Port, and Data Centers)
Mobile Substation Market, by Region
  • Americas
  • Europe
  • APAC
  • Middle East & Africa
Available Customizations
With the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:

Company Information:
Detailed analysis and profiles of additional market players (up to 5)
 
About MarketsandMarkets™
 
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 5000 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "RT" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Rohan
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441
sales@marketsandmarkets.com

Thursday, 12 April 2018

Mobile Substation Market worth 1,136.9 Million USD by 2023

According to the new market research report "Mobile Substation Market by Application (Industrial (Metals & Mining, Oil & Gas, Construction, Port, and Data Centers), and Utilities), and Region (Midle East & Africa, Americas, Europe, and Asia Pacific) - Global Forecast to 2023 ", the mobile substation market is expected to grow from an estimated USD 789.3 Million in 2018 to USD 1,136.9 Million by 2023, at a CAGR of 7.57% between 2018 and 2023. The mobile substation is also known as portable substation or compact power house. Factors driving the growth of this market include the ease of transportation, time-saving, flexibility, and easy installation of the mobile substation. Moreover, mobile substations can be installed in a limited space and can be easily relocated without difficulties. Transportability, short startup and commissioning time, reduced mechanical footprint, and non-requirement of civil work are some key benefits which are expected to drive the growth of mobile substation in the global market during the forecast period.  

 
Browse 32 market data Tables and 34 Figures spread through 97 Pages and in-depth TOC on "Mobile Substation Market"

Market for utilities application expected to grow at higher CAGR during the forecast period

Mobile substations can be useful for emergency response as back-up units and are also useful in cases where the energy distribution requires to be provided or reinstated in a short span of time. Mobile substations are utilized in both, utilities and industrial applications.  Planned maintenance, disaster response, rapid expansion of transmission capacity are some use cases where mobile substations have delivered proven outcomes for utilities. Mobile substations are used to provide temporary power supply during unplanned repairs. Moreover, in the times of planned maintenance, mobile substations can reduce or even eliminate the need for extended electricity outages.

Various companies, including Siemens, General Electric, Eaton, and MEIDENSHA provide mobile substations to the utility industry. For instance, in 2017 Siemens delivered 2 mobile substations for National Grid SA, the transmission operator of Saudi Electricity Co. Siemens is expected to design 2, 380kV mobile substations with transformer rating of 502 MVA each. General Electric supplied several mobile substations in the utility sector including for Saudi Electricity Company from Saudi Arabia and E.ON SE electric project in Spain.

Mobile substation market in the Middle East & Africa to grow at the highest CAGR during forecast period

Middle East & Africa not only account for the largest market share followed by the Americas but is also expected to grow at the highest CAGR during the forecast period. Rapid electrification in Africa along with demand from the metals & mining industry in Africa is expected to drive the growth of the global mobile substation market.

Politically unstable situations in Middle East countries, such as Iraq, are reducing day by day and the government is making efforts to provide basic amenities. As a part of this, in 2017 the Ministry of Electricity, Iraq ordered 12 mobile substations for its utilities. This increase in power supply due to the installation of new substations are expected to overcome power shortage issues in Iraq. Moreover, in 2014 Ministry of Electricity, Iraq ordered 16 mobile substations from CG Power (India). These substations are expected to be deployed throughout Iraq for utilities and industries to provide interim grid connections and temporary power supplies. Recently, in 2017 the Aktif Group delivered 10 mobile substations to the Ministry of Electricity Iraq. Countries such as Angola, Algeria, Mozambique, and Libya, among others are also leading to the high demand for mobile substations.

Key players in this market are Siemens (Germany), ABB (Switzerland), Eaton (Ireland), General Electric (US), CG Power (India), and MEIDENSHA (Japan). Other companies covered in this report are WEG (Brazil), AZZ (US), TGOOD (Hong Kong), Powell Industries (US), Elgin Power Solutions (US), Matelec Group (Lebanon), Aktif Group (Turkey), PME Power Solutions (India), EKOS Group (Turkey), Efacec (Portugal), and Delta Star (US).

About MarketsandMarkets™
 
MarketsandMarkets™ provides quantified B2B research on 30,000 high growth niche opportunities/threats which will impact 70% to 80% of worldwide companies’ revenues. Currently servicing 5000 customers worldwide including 80% of global Fortune 1000 companies as clients. Almost 75,000 top officers across eight industries worldwide approach MarketsandMarkets™ for their painpoints around revenues decisions.

Our 850 fulltime analyst and SMEs at MarketsandMarkets™ are tracking global high growth markets following the "Growth Engagement Model – GEM". The GEM aims at proactive collaboration with the clients to identify new opportunities, identify most important customers, write "Attack, avoid and defend" strategies, identify sources of incremental revenues for both the company and its competitors. MarketsandMarkets™ now coming up with 1,500 MicroQuadrants (Positioning top players across leaders, emerging companies, innovators, strategic players) annually in high growth emerging segments. MarketsandMarkets™ is determined to benefit more than 10,000 companies this year for their revenue planning and help them take their innovations/disruptions early to the market by providing them research ahead of the curve.

MarketsandMarkets’s flagship competitive intelligence and market research platform, "RT" connects over 200,000 markets and entire value chains for deeper understanding of the unmet insights along with market sizing and forecasts of niche markets.

Contact:
Mr. Salgarkar
MarketsandMarkets™ INC.
630 Dundee Road
Suite 430
Northbrook, IL 60062
USA : 1-888-600-6441
sales@marketsandmarkets.com